
An invalid Israeli Value Added Tax (VAT) number costs you money. The Israel Tax Authority (ITA) can deny your input VAT credits when a supplier number or invoice is wrong. Poor bookkeeping draws a penalty of 1% of annual turnover under Section 95(a) of the Israeli VAT Law, with a floor of NIS 359 (New Israeli Shekel) per month, confirmed unchanged for 2026 in the law’s consolidated text. Late payment adds arrears interest under Section 96, starting at 0.25% of the unpaid tax per week.
Israel has no VIES-style single public portal that validates a VAT number by the number alone. This guide gives you a complete, step-by-step process to verify an Israel tax registration number and stay VAT compliant. New to VAT mechanics? Start with our VAT vs sales tax guide.
What Is an Israeli VAT Number?
An Israeli VAT number is a 9-digit identifier the Israel Tax Authority issues to a licensed dealer (Osek Murshe). For a company, it equals the Company Registration Number from the Israeli Corporations Authority. For a sole trader, it equals the Teudat Zehut, the national identity number. It carries no country prefix and appears on tax invoices, VAT returns, and ITA correspondence.
People sometimes call it the Business Identification Number (BID), but that umbrella term just points to one of the identifiers mapped below.
Which Tax Numbers Does Israel Use?
Israel uses several overlapping 9-digit identifiers, and the VAT dealer number is only one of them. The table maps each identifier to its issuer and its relationship to the VAT number.
| Identifier | Issuer | Who holds it | Relation to the VAT number | Source |
|---|---|---|---|---|
| Teudat Zehut (9-digit national ID with check digit) | Ministry of the Interior | Israeli citizens and residents | Equals the VAT dealer number for a sole trader | Israel Tax Authority |
| Company Registration Number (9 digits, conventionally starts with 5) | Israeli Corporations Authority (Registrar of Companies) | Incorporated companies | Equals the VAT dealer number for a company | Israeli Corporations Authority |
| Osek Murshe / VAT dealer number (9 digits) | Israel Tax Authority | VAT-charging dealers | The VAT number itself | Israel Tax Authority |
| Income Tax File Number | Israel Tax Authority | Businesses and individuals filing income tax | Separate file, not the VAT number | Israel Tax Authority |
| Tax Deduction File Number | Israel Tax Authority | Employers withholding payroll | Separate file, not the VAT number | Israel Tax Authority |
The VAT file itself is opened with Form 821 at the ITA VAT division, separate from the Form 5329 income tax file and National Insurance registration, per the Israel Tax Authority.
What Is the Israeli VAT Number Format?
An Israeli VAT number is 9 digits, with no country code, spaces, or hyphens. Incorporated businesses conventionally start with 5, a Registrar of Companies numbering convention rather than a rule written into the Companies Law, 5759-1999. Sole traders use their Teudat Zehut, which can start with any digit. The registrar convention assigns leading digits by entity type.
Most rejected numbers fail on simple entry errors:
- Wrong digit count, such as 8 digits instead of 9.
- Added country codes, spaces, or hyphens.
- Transposed digits from manual entry.
- Dropped leading zeros, which spreadsheets silently strip.
How Do You Check the Checksum Offline?
An Israeli 9-digit ID validates against a Luhn-type checksum, so you catch most typos before any lookup. Multiply each digit alternately by 1 and 2, from left to right. If a product exceeds 9, add its two digits together. Sum every result. A valid number’s total divides evenly by 10.
Treat this as a convention, not a guarantee. The Luhn-type check digit is documented for the Teudat Zehut on Israel’s own ID-number reference, but no official ITA or Corporations Authority publication codifies a checksum for Company Registration Numbers. The Registrar applies the same mod-10 scheme by administrative convention, so the offline check is a first filter, not proof of a live, valid dealer.
Simplify global indirect tax compliance across every market
Book a demo to automate your filings
Does Israel Have a VIES-Style VAT Lookup?
No. Israel has no single free public portal that validates a VAT number by the number alone, unlike the European Union’s VAT Information Exchange System (VIES). By design, VIES covers only the 27 EU member states plus Northern Ireland, so it structurally cannot cover Israel.
Verification in Israel runs through three real channels: the Israeli Corporations Authority register, a cross-reference against the counterparty’s identity, and the ITA e-invoicing allocation number on qualifying invoices. The ITA’s closest online service only verifies that invoice line-item details match data already reported against a previously issued allocation number, not a bare VAT-ID lookup. Our EU VAT number validation guide covers the VIES route for European counterparties.
How Do You Verify an Israeli VAT Number Online, Step by Step?
Confirm the checksum, look the entity up in the Israeli Corporations Authority register, cross-reference the number against the invoice, and confirm active dealer status. There is no one-click portal, so follow each step in order.
- Run the offline checksum check. Confirm 9 digits and a total divisible by 10.
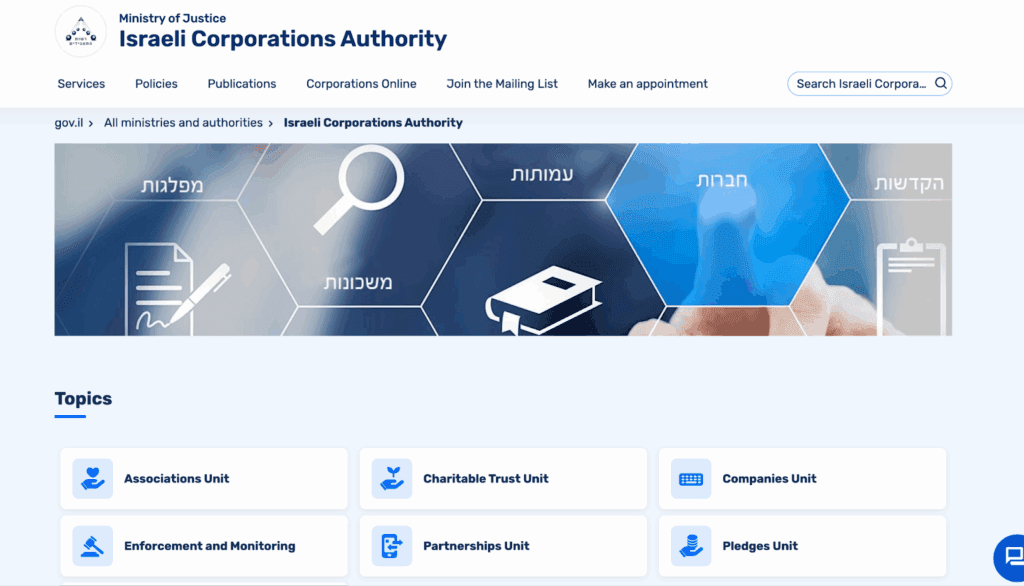
- Search the Corporations Authority portal, officially titled “Corporations Online” (Tagidim Online), at its company-search page, by company number or name. The interface is primarily in Hebrew.
- Read what the free search returns: company number, Hebrew and English name, company type, legal status, incorporation date, registered address, and stated purpose. A certified full extract with directors, shareholders, and share capital is a paid service via the gov.il company extract page.
- Cross-reference the identity. The Company Registration Number or Teudat Zehut must match the number and name on the invoice.
- Log the result with the date checked, because no portal stores historical status.
The register confirms that a company exists and its legal status. It does not confirm active VAT registration, because dealer status lives with the ITA, not the registrar. Confirm active status by requesting the supplier’s ITA registration certificate directly, or by checking the e-invoicing allocation number on qualifying invoices. For a foreign counterparty with no Israeli register presence, ask for the certificate the Israel-resident fiscal representative holds; see our Israel VAT registration for foreign companies guide.
How Does Israel’s E-Invoicing Mandate Change VAT Verification?
Israel’s clearance-model e-invoicing requires an ITA-issued allocation number (mispar haktzaa) on B2B (business-to-business) tax invoices above a set value. The buyer needs that number before deducting input VAT, under the ITA’s “Israel Invoice” program. Invoice-level clearance is now the de facto real-time VAT verification layer, and the threshold phases down on a published schedule.
| Effective date | Allocation-number threshold (invoice value before VAT) | Source |
|---|---|---|
| From 5 May 2024 | Above NIS 25,000 | Israel Tax Authority (Israel Invoice) |
| 2025 | Above NIS 20,000 | Israel Tax Authority (Israel Invoice) |
| From 1 January 2026 | Above NIS 10,000 | ITA VAT Execution Directive 10/2025 |
| From 1 June 2026 | Above NIS 5,000 | ITA VAT Execution Directive 10/2025 |
ITA VAT Execution Directive 10/2025, published 7 December 2025, confirms the NIS 10,000 and NIS 5,000 steps for 2026. No competitor coverage explains this transactional layer.
What Is the Israeli VAT Registration Threshold?
Israel has no single EU-style registration threshold. NIS 122,833 for 2026 is the ceiling that separates an Osek Patur (exempt small dealer) from an Osek Murshe (licensed dealer), per the Israel Tax Authority VAT rates and amounts page. That ceiling was NIS 120,000 in 2024 and 2025 and is re-indexed to inflation every 1 January. A dealer must register by the day business activity begins, under Section 52(a). The standard VAT rate is 18%, effective 1 January 2025, per the Knesset.
| Dealer status | Turnover threshold (2026) | Obligations | Source |
|---|---|---|---|
| Osek Patur (exempt dealer) | Up to NIS 122,833 | Cannot charge VAT, cannot reclaim input VAT, files an annual declaration | Israel Tax Authority (gov.il) |
| Osek Murshe (licensed dealer) | Above NIS 122,833 | Charges 18% VAT, files periodic returns, reclaims input VAT | Israel Tax Authority (gov.il) |
Do Foreign Companies Need an Israeli VAT Registration?
Yes. Non-resident companies with business activity in Israel must register regardless of turnover. Under Section 60(a) of the VAT Law, a non-resident must appoint an Israel-resident representative (fiscal representative) within 30 days of starting activity, and file that representative’s written consent with the ITA. The representative is treated as the taxable person and shares liability.
See our Israel VAT registration for foreign companies guide for the full fiscal representative process.
What Happens If You Use an Invalid Israeli VAT Number?
You face denied input VAT deductions, penalties, and arrears interest. A missing or invalid allocation number blocks the buyer’s input VAT credit outright. Late registration itself is not a percentage fine; the widely repeated “1% of turnover” figure is actually the Section 95(a) bookkeeping penalty. The table lists each verified penalty with its base, effective date, and source.
| Violation | Penalty and base | Effective date | Source |
|---|---|---|---|
| Failure to keep proper books (Section 95(a)) | 1% of total annual turnover, minimum NIS 359 per month | Minimum unchanged for 2026 (raised from NIS 350 on 1 July 2024) | Israel Tax Authority (VAT Law) |
| Late payment of VAT (Section 96) | 0.25% of unpaid tax per week for the first six months, then 0.5% per week | Current | Israel Tax Authority (VAT Law) |
| Late filing of a periodic VAT report (Section 94) | NIS 239 per two-week period of delay | Effective 1 January 2025 | Israel Tax Authority (VAT Law) |
| Failure to register when required (Section 117) | Criminal: up to 1 year imprisonment, or up to 5 years with intent to evade tax | Current | Israel Tax Authority (VAT Law) |
| Invalid number or missing allocation number | Buyer’s input VAT deduction denied | Current | Israel Tax Authority (Israel Invoice) |
How Should Finance Teams Check Israeli VAT Numbers for Suppliers?
Verify at onboarding, re-verify quarterly and before large payments, and keep a dated internal log. No Israeli portal stores historical status, so your log is the only audit trail proving a supplier was valid when you paid. Capture the number checked, the Corporations Authority result, the allocation number on large invoices, and the date.
This log protects your input VAT claim if the supplier is later deregistered, because the ITA judges your deduction on the status at the time of the transaction, not today.
How We Help With Israeli VAT Compliance
Commenda’s global indirect tax platform handles Israeli VAT registration, filings, and ongoing compliance monitoring in one place, so your team knows every dealer status and deadline is tracked. It connects to your finance stack through 100+ ERP, API, and custom integrations. Use our global tax ID verification tool to check counterparties at onboarding, and the compliance calendar to stay ahead of filing dates. Expanding into Israel from abroad? Our Israel VAT registration for foreign companies guide walks through the fiscal representative requirement.
Book a demo to get a free Israeli VAT compliance assessment.
About the author

Sam is a seasoned expert in sales tax, leading Commenda's effort to build the worlds most comprehensive database of global tax rules and business regulations. At Silverhaze Partners, he worked in early-stage venture capital, where he saw firsthand how tax complexity and regulatory friction hold back startups from scaling internationally. That experience now powers his work at Commenda-bringing clarity, precision, and real-world insight to one of the most frustrating parts of doing business globally.
Disclaimer: Commenda and its affiliates do not provide tax, accounting, or legal advice. This material has been prepared for informational purposes only, and is not intended to provide or be relied on for tax, accounting, or legal advice. You should consult your own tax, accounting, and legal advisors before engaging in any related activities or transactions.





