Do business in Poland. Without the mess.
Poland is Central and Eastern Europe's largest economy and an EU gateway to regional markets. With digital incorporation in as little as 1-3 days and a 9% tax rate for qualifying small businesses, it's one of Europe's most cost-effective jurisdictions for foreign entities.

Trusted by global businesses
Why Poland
Why Poland for your next entity
Poland consistently outperforms its regional peers on FDI inflows, infrastructure development, and workforce quality. The sp. z o.o. (private limited company) offers limited liability with a PLN 5,000 minimum share capital and can be registered digitally via the S24 online system in 1-3 business days. The 9% corporate tax rate for small taxpayers with revenue under €2M is among the lowest in the EU. Poland's IP Box at 5% on qualifying income makes it a serious jurisdiction for IP holding. As an EU member with strong logistics networks, it's the natural gateway for companies entering Eastern European markets.
Explore incorporation options- 19%Standard corporate tax rateApplied to taxable income for companies above the small taxpayer threshold
- 9%Small taxpayer corporate tax rateFor companies with annual revenue under €2M, one of the EU's lowest rates
- PLN 5KMinimum share capital (sp. z o.o.)Low entry barrier for foreign companies forming a Polish limited company
- 1-3 daysIncorporation via S24 digital systemPoland's online KRS registration makes it one of the fastest EU incorporations
Product Suite
One platform
Every jurisdiction, no gaps
Built for finance teams running international operations without a dedicated compliance function. This is the infrastructure you should have had from day one.
- Learn more
Entity Management
Formation, maintenance, and oversight for subsidiaries across 80+ countries.
- Learn more
Global Indirect Tax
VAT, GST, and sales tax obligations tracked, filed, and confirmed.
- Learn more
Transfer Pricing
Intercompany policy, documentation, and filing, built to OECD standards.
- Learn more
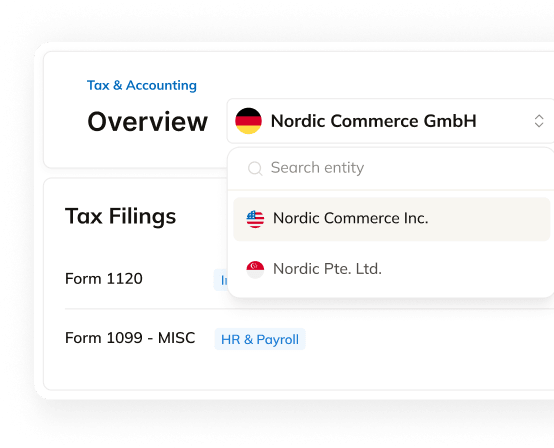
Tax & Accounting
Consolidated financial reporting and local corporate tax filings. One audit trail.
Entity types
Choose the right structure for your business
Recommended
sp. z o.o. (Spolka z ograniczona odpowiedzialnoscia)
Poland's private limited company is the default structure for foreign market entry. Limited liability, a PLN 5,000 minimum share capital, and the option for digital formation via S24 make it the fastest and most cost-effective EU incorporation available.
Benefits
- PLN 5,000 minimum share capital (approximately €1,100)
- Digital incorporation via S24 in as little as 1-3 business days
- No residency requirement for directors or shareholders
- 9% corporate tax for small taxpayers with revenue under €2M
- IP Box: 5% effective tax rate on qualifying intellectual property income
- Single-member structure permitted for wholly owned subsidiaries
Key considerations
- KRS (National Court Register) registration required
- 23% VAT registration required for trading entities
- At least one director (czlonek zarzadu) must be designated
- Annual financial statements must be filed electronically with KRS
- S24 incorporations use a standardized deed; custom articles require a notary
How it works
From kickoff to open for business in Poland
Incorporating in a new country means unfamiliar filings, local requirements, and moving parts across multiple vendors.
We handle all of it so you don't have to.
Day 1
Onboarding
Your details submitted once. Entity name checked, documents collected, filings kicked off. No back-and-forth.
Days 1–3
Entity confirmed
Incorporation done. Formation documents, company number, and registered address live in your Commenda dashboard.
Week 1–2
Tax setup
Tax registrations filed, banking guidance underway. Compliance calendar set for your jurisdiction.
Week 2
Open for business
You're operational in a new market. Without a single trip to a government office.
G2 Reviews
Rated by the teams using it
Scores from finance and legal leads handling compliance globally.
Entity Management
#1 Ranked9.6/ 10Set up your entity and keep it in good standing. Filings, records, and renewals tracked in one place.
Corporate Tax & Compliance
Top Rated9.1/ 10Every tax deadline on one calendar. Corporate returns and statutory filings handled without the back-and-forth.
Sales Tax & VAT/GST
Commenda Leads9.4/ 10Handle VAT, GST, and sales tax in every country you operate in, and manage it all in one place.
Poland resources
Everything you need for your Poland operations
Detailed guides on tax, compliance, and business structure in Poland.
- Incorporation
How to Incorporate in Poland
Step-by-step guide to forming a sp. z o.o. via Poland's S24 digital system, from document preparation to KRS registration and VAT enrollment.
Read guide - Compliance
Poland Corporate Compliance Guide
Annual KRS filings, CIT returns, and VAT obligations for entities operating in Poland.
Read guide - Tax
Poland Corporate Tax and IP Box Overview
How Poland's 9% SME rate, 19% standard CIT, and 5% IP Box regime work together for foreign-owned entities.
Read guide - Expansion
Expanding into Central Europe via Poland
Why multinationals use Polish entities as their CEE hub and how to structure for cross-border tax efficiency.
Read guide
FAQ
Common questions
Join hundreds of international businesses growing fast with Commenda
Tell us where you're expanding and we'll scope the requirements, handle the filing, and keep your entity compliant, usually within 24 hours of kickoff.